
Procurement teams often find themselves juggling between two major financial performance indicators: cost avoidance and cost savings. Although they may sound similar, these two terms have distinct meanings and roles in purchasing strategies.
Understanding the difference between cost avoidance and cost savings can significantly improve how organizations track value, justify procurement decisions, and report achievements to stakeholders.
What is Cost Avoidance?
Cost avoidance refers to actions that prevent a company from incurring additional costs in the future. Rather than reducing current spending, cost avoidance focuses on preventing cost increases. It is a proactive strategy that helps maintain profitability by shielding the organization from potential financial impact.
Examples of Cost Avoidance
- Negotiating a price freeze in a contract to avoid supplier price hikes for the next three years.
- Switching to a supplier with better payment terms to avoid late fees or financing charges.
- Investing in preventative maintenance to avoid costly repairs or replacements.
These actions don’t generate immediate savings but help maintain cost stability and protect budgets over time.
What is Cost Savings?
Cost savings involve a direct reduction in expenditures. It is a reactive or corrective measure that lowers the actual spending from what was previously incurred. This is often more visible in budgets and financial reports.
Examples of Cost Savings
- Renegotiating a contract and reducing the price of a product from $10 to $8.
- Replacing an expensive supplier with a lower-cost, quality-approved alternative.
- Buying in bulk to take advantage of volume discounts.
These examples show how cost savings produce a measurable and immediate financial impact.
Main Differences Between Cost Avoidance and Savings
While both strategies improve the financial health of an organization, they differ in timing, measurability, and how they’re reported.
Timing
Cost avoidance occurs before a cost is incurred. It is forward-looking and focuses on mitigating future risks or cost increases. Cost savings, on the other hand, reflect reductions in actual expenses that have already occurred or are currently being paid.
Measurability
Cost savings are quantifiable and appear in financial statements and procurement reports. It is easily tracked using budget comparisons. In contrast, cost avoidance is harder to measure because it relates to costs that never materialized. It often requires justification or assumptions based on market trends, forecasts, or historical price increases.
Budget Impact
Cost savings reduce the current year’s budget requirements. It immediately frees up funds for reinvestment or savings. Cost avoidance, although valuable, does not directly lower budgeted amounts but prevents potential budget overages in the future.
How to Calculate Cost Avoidance
Calculating cost avoidance requires an understanding of the market or baseline cost trends. The formula is:
Cost Avoidance = Potential Future Cost - Cost After Avoidance Strategy
Example:
A supplier is expected to raise prices from $10 to $12 next quarter. You negotiate to keep the price at $10.
Cost avoidance = $12 - $10 = $2 per unit
Cost Savings Calculation
Cost savings is more straightforward. The formula is:
Cost Savings = Original Cost - Reduced Cost After Savings Strategy
Example:
You were paying $15 per unit but negotiated a price of $11.
Cost savings = $15 - $11 = $4 per unit
This $4 saving is reflected directly in the procurement budget.
Best Practices for Cost Savings and Cost Avoidance
Both cost savings and cost avoidance should be incorporated into procurement strategies. While cost savings delivers visible short-term results, cost avoidance contributes to long-term financial health.
Cost Avoidance Practice: Build Strong Supplier Relationships
Work collaboratively with suppliers to identify opportunities to lock in favorable terms. Open communication can result in cost avoidance through early warnings about market shifts, advance notice of pricing changes, and opportunities for bundled services.
Cost Avoidance Practice: Use Strategic Contracting
Include clauses such as price caps, long-term discounts, or no automatic increases in vendor contracts. These contractual protections can prevent future price hikes or service fees.
Cost Savings Practice: Perform Regular Spend Analysis
Analyzing procurement data helps identify high-cost areas, redundant vendors, or items where costs have increased without justification. Use this insight to make informed cost-cutting decisions.
Cost Savings Practice: Consolidate Suppliers
Consolidating purchases with fewer suppliers can lead to better pricing tiers and volume-based discounts. It also simplifies vendor management, which can indirectly reduce costs.
Cost Savings Practice: Leverage Technology and Automation
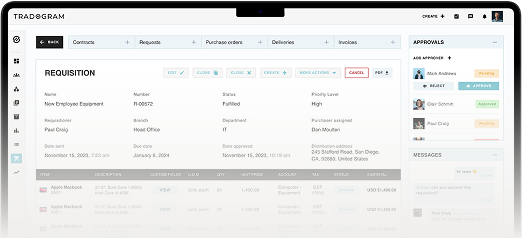
Use procurement software to automate repetitive tasks, reduce manual errors, and increase spending visibility. Tools like budget tracking dashboards can help identify opportunities for savings across categories.
Improve Savings with Tradogram
Understanding and differentiating cost avoidance from cost savings is vital for accurate procurement reporting and effective decision-making. While cost savings is easier to quantify and immediately beneficial, cost avoidance plays a crucial role in future-proofing the business from financial risks.
Both strategies should be tracked using reliable tools. A great option is Tradogram’s Budget Management System, which provides procurement professionals with real-time visibility into budgets, helping ensure every dollar spent or avoided is accounted for accurately.
By using both cost savings and avoidance strategies, businesses can build more resilient procurement functions and long-term financial stability.