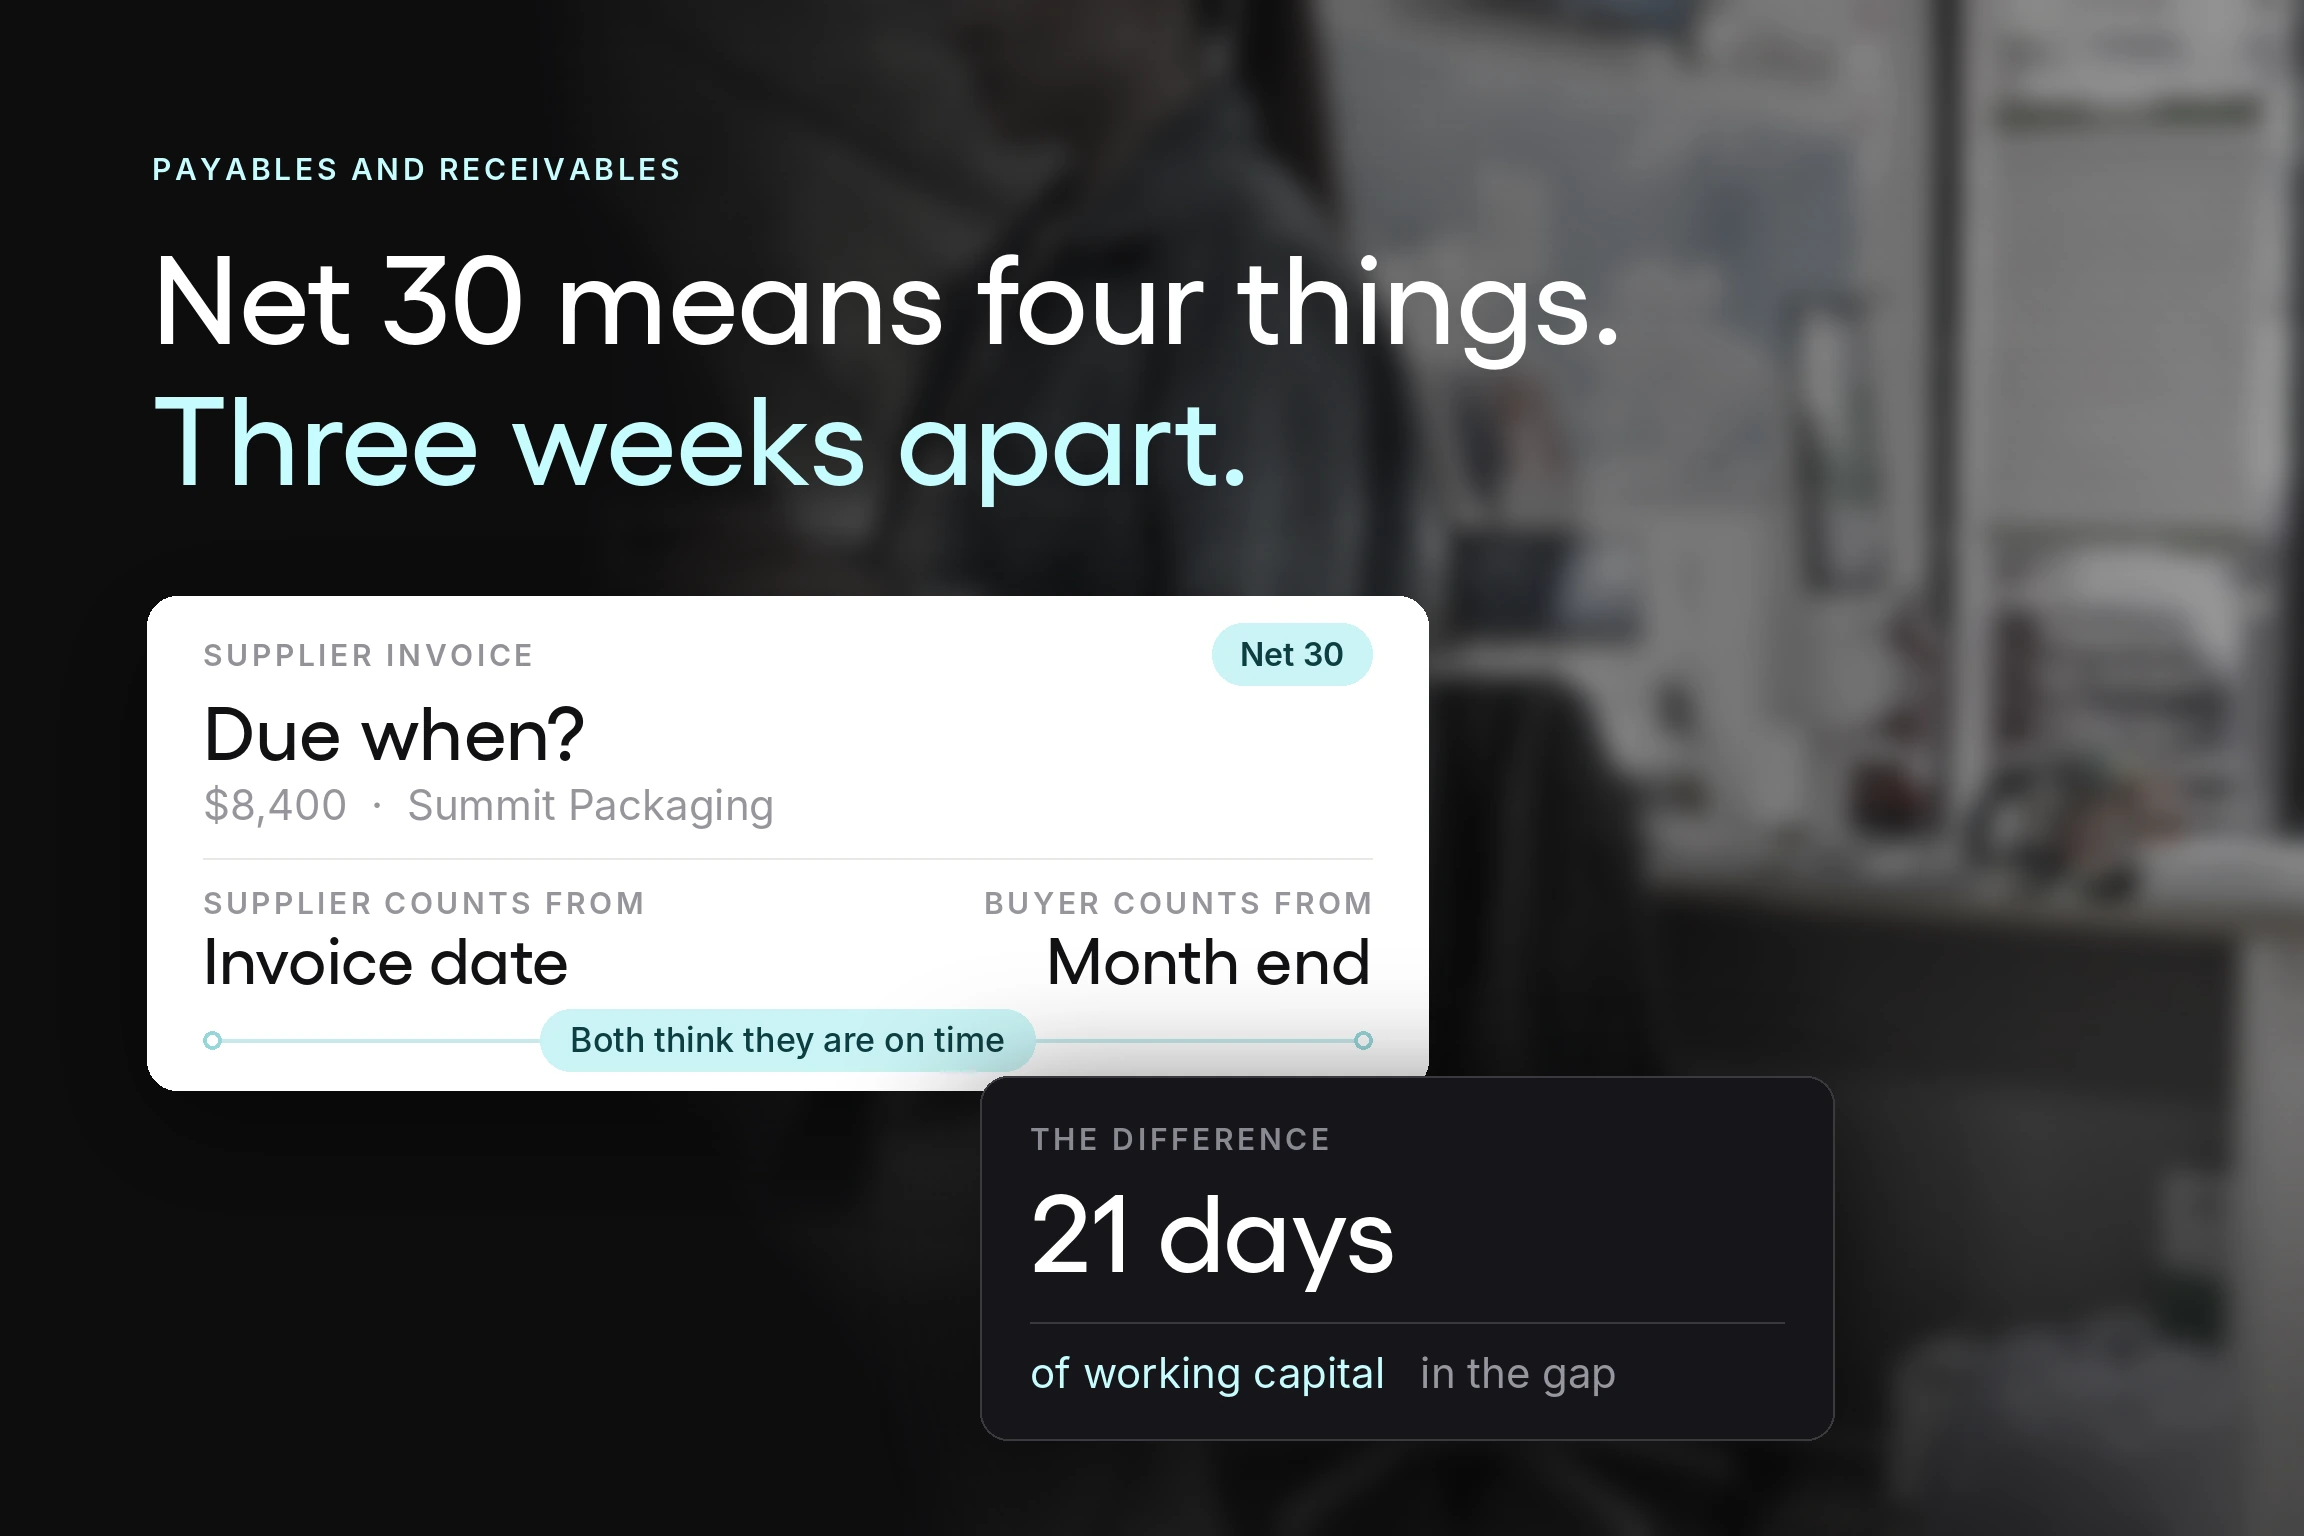

Net 30 is the most common payment term in small business, but it doesn't have one agreed meaning. To the supplier who issued the invoice, the thirty days begin on the invoice date. To the buyer processing it, they often begin when the invoice arrived, or when it cleared approval, or on the last day of the month in which it was received.
Every one of those readings is defensible. Between the earliest and the latest sits about three weeks of working capital, and both parties believe they are settling on time.
The same definitional slack runs through the rest of the subject. In most small businesses, accounts payable and accounts receivable are defined as two jobs: one belongs to whoever pays the bills, the other to whoever sends them. Defined that way, each is measured on its own terms, and the space between them is absorbed by whoever is watching the bank balance.
That space has a name. The cash conversion cycle is the time between paying for something and being paid for what you did with it, and for most small businesses it runs longer than it needs to because the two halves are run as separate jobs against separate clocks.
At Tradogram, we have helped thousands of organizations digitize their procurement and payables processes, and the problem we see most often is not weak discipline on one side or the other. It is two sides keeping different books on the same cash. The practices below are organized so that each one covers both halves of the ledger, because almost every improvement that helps one side either helps or hurts the other.
Key Takeaways
- Small business payables and receivables are one cash flow problem, not two processes. Extending payment terms on the payables side and tightening them on the receivables side are the same lever pulled in opposite directions, and doing one without the other produces no net change.
- The controls that stop payment fraud cost almost nothing to install, and fraud thrives where they are missing or easy to override. The ACFE's 2026 Report to the Nations, drawn from 2,402 cases, found a median loss of $104,000 and a typical case running 12 months before detection. More than half of cases involved a lack of internal controls or an override of controls already in place.
- Strong payables operations run leaner, and the gap is measurable. The Hackett Group found top-performing procurement organizations run with 31% fewer FTEs at 19% lower cost than their peers, while Ardent Partners reports an average invoice cost of $9.84 and 8.2 days, with an 18.4% exception rate.
- Early payment discounts are usually worth taking, and the arithmetic is simple enough to check. A 2% discount for paying 20 days early is an annualized return of roughly 37%, which beats almost anything else a small business can do with short-term cash. The condition is that you have the cash, and forecasting is what tells you whether you do.
- Days payable outstanding and days sales outstanding only mean something read together. A DPO of 45 looks strong until you see a DSO of 60, at which point the business is financing its customers with supplier credit and will run out of room.
Why payables and receivables have to be managed as one problem
The cash conversion cycle is the number of days between money leaving for inputs and money arriving from customers, and it is usually positive for a small business.
That positive gap is the reason cash flow management is a discipline. Profitable businesses fail inside it. Most cash flow challenges in a small business are timing problems. That is a more solvable category than it feels at the time: the money is coming, but it is simply not coming yet, and the financial obligations in between don't wait.
Cost pressure widens the gap before anything else does. The Federal Reserve Banks' 2026 Report on Employer Firms, which surveyed 6,525 firms with 1 to 499 employees, found 77% reported rising costs, tariff costs, or both. When input prices move faster than the terms you have agreed on, the cycle stretches without anyone changing a process.
Three measures describe it, and you have to read them together.
Days payable outstanding. The average number of days you take to pay suppliers. Higher generally helps cash, up to the point where it damages vendor relationships or costs you discounts.
Days sales outstanding. The average number of days customers take to pay you. Lower always helps.
The gap between them. If DSO (Days Sales Outstanding) exceeds DPO (Days Payable Outstanding), you are funding your customers out of your own working capital. If DPO exceeds DSO comfortably, your suppliers are funding your operations. That is a stronger position, and it holds only as long as those suppliers are paid on the terms you agreed to.
Most small business advice addresses one of these at a time. "Negotiate longer payment terms" and "invoice faster" are both reasonable, and neither is a strategy on its own, because the useful number is the distance between them.
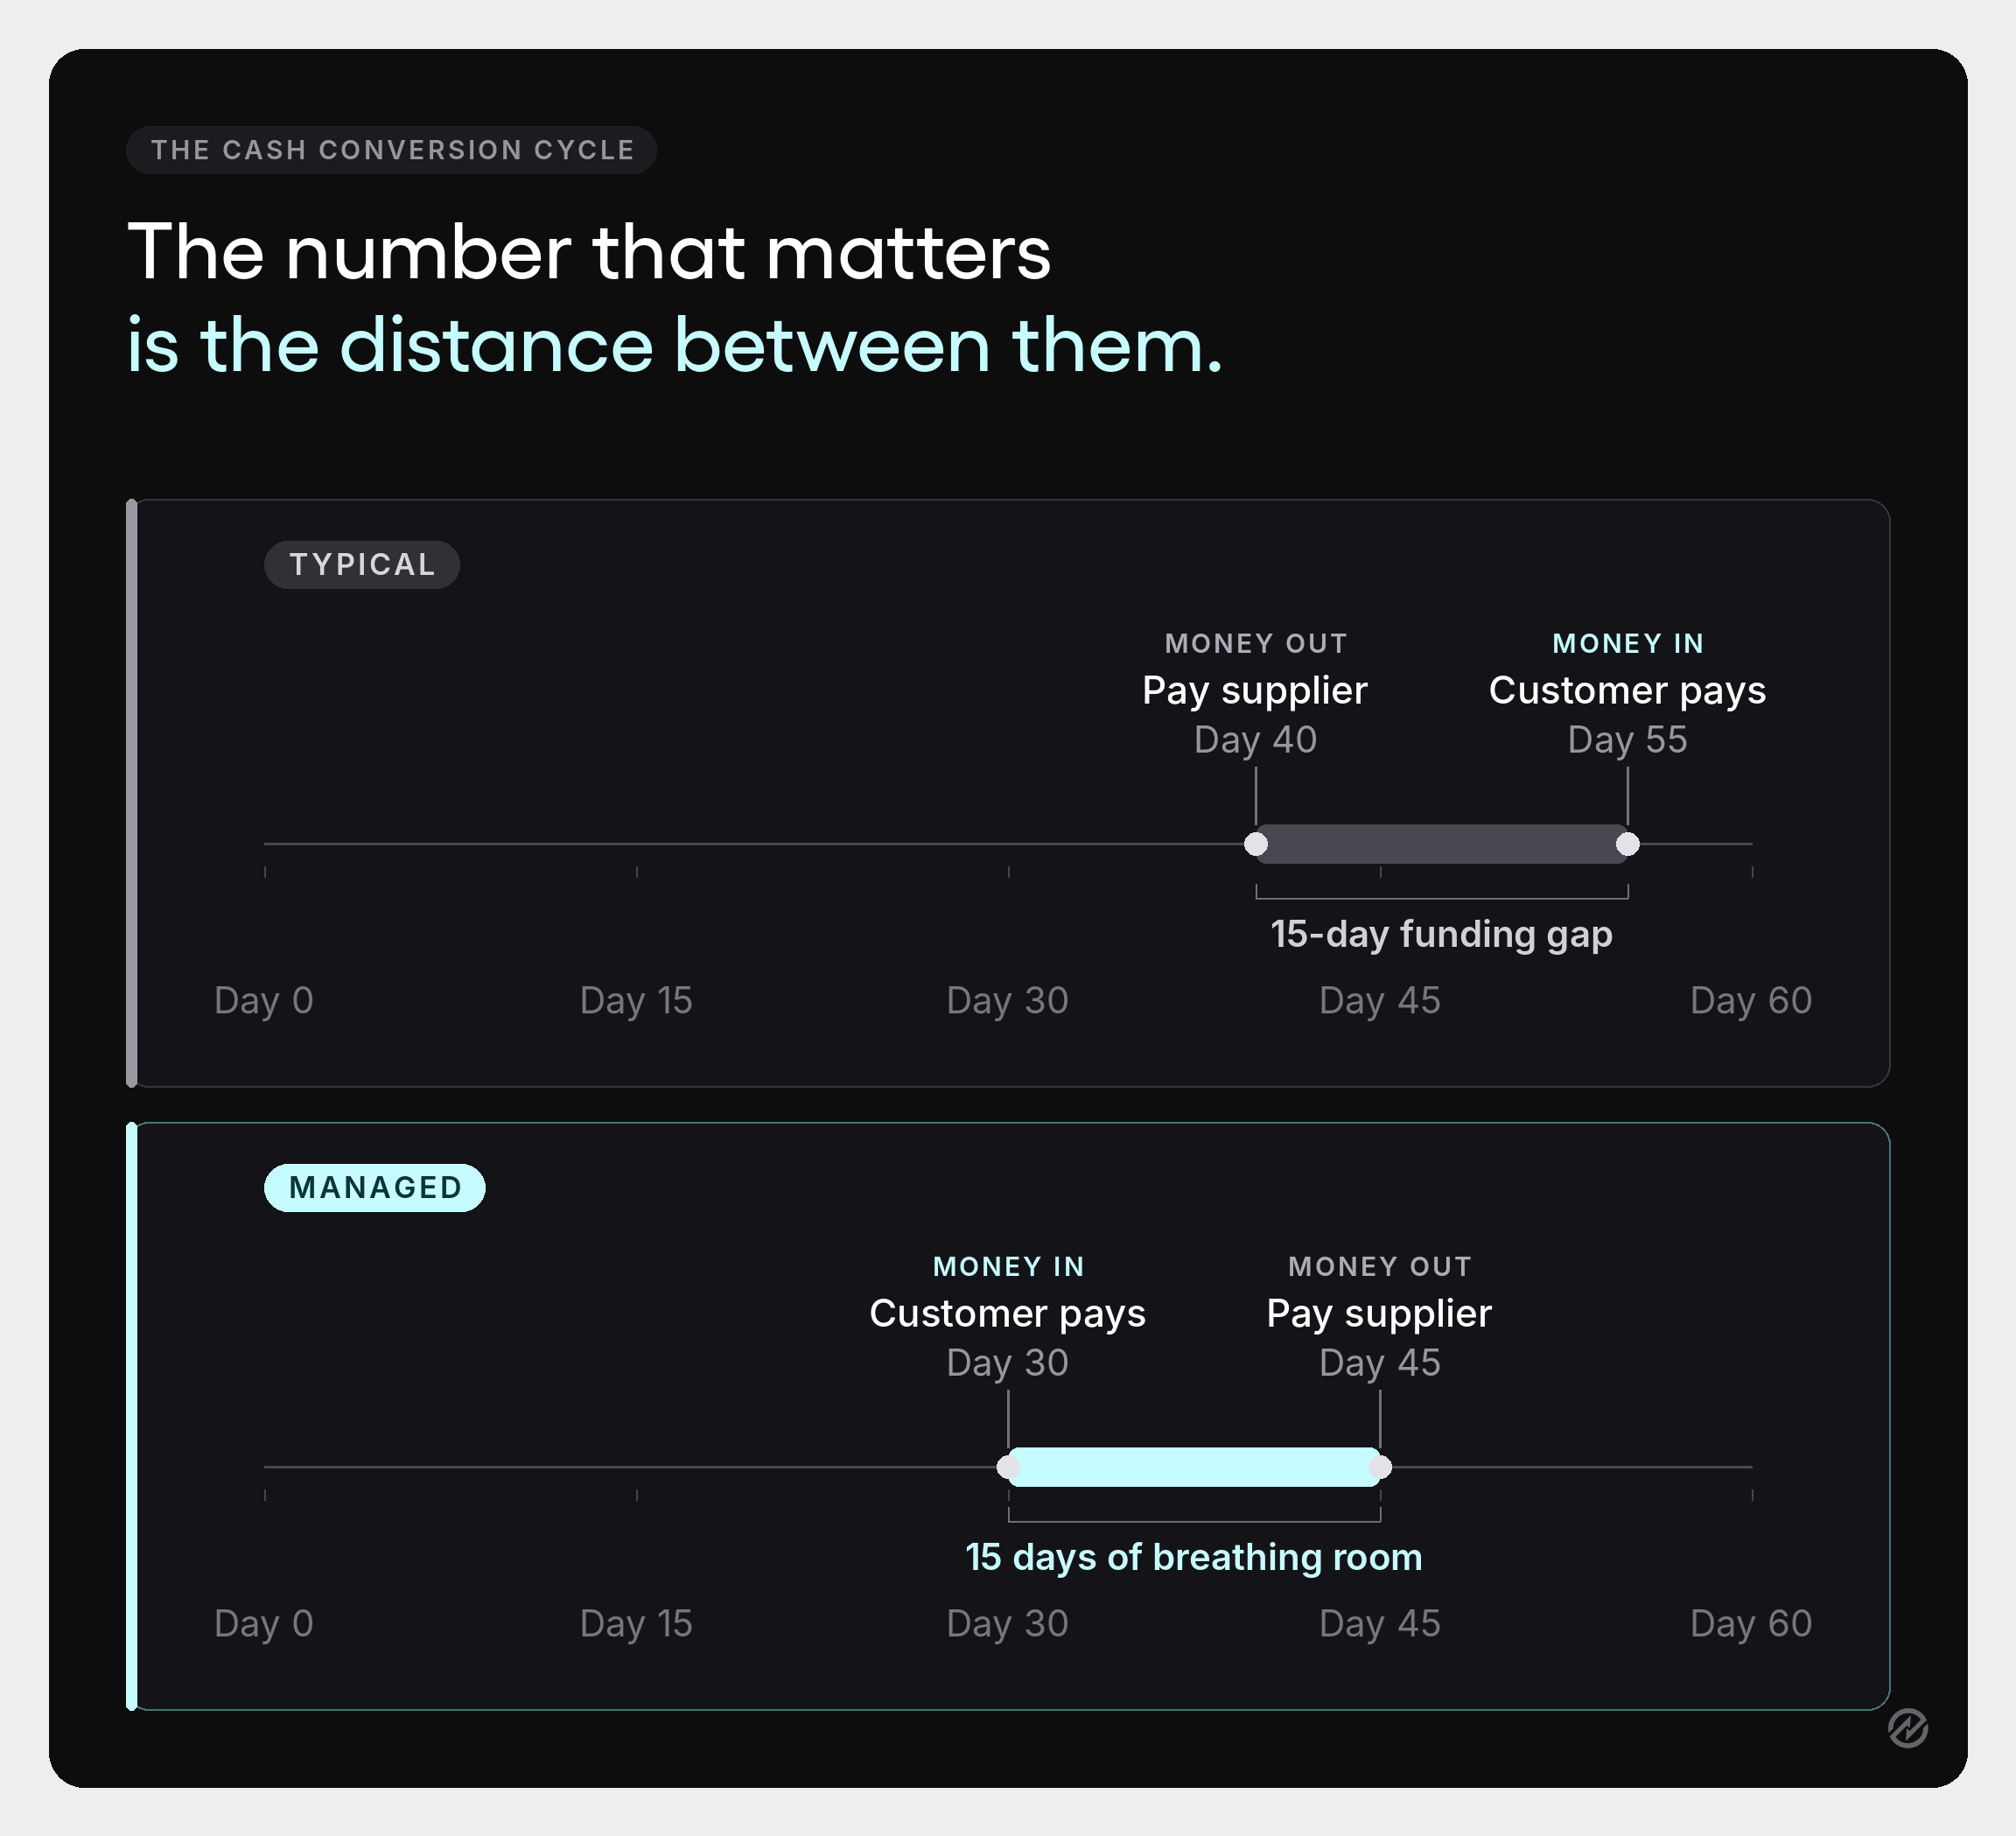
The practical version: pick a target for the gap and manage both sides toward it. A business with a 30-day DSO and a 45-day DPO has 15 days of breathing room and can plan. A business with a 55-day DSO and a 40-day DPO is 15 days short every cycle and will feel it as a permanent low-grade cash flow challenge that no single fix resolves.
Set the terms deliberately, on both sides
Accounts payable refers to what you owe suppliers; accounts receivable is what customers owe you. Payment terms are the single lever that moves both, and most small businesses accept whatever they are offered on one side while never stating them clearly on the other.
On the payables side. Negotiating favorable payment terms is a conversation most small businesses never have, assuming terms are fixed. They generally are not, particularly with suppliers who value the relationship.
Net 45 instead of net 30 on a significant supplier is 15 days of working capital at no cost. What makes this negotiable is reliability: a record of timely payments is the only leverage that matters here, because a supplier will extend terms to a customer who pays on the day they say they will and will not extend them to one who does not.
The mistake to avoid is extending terms by simply paying late. Late payment costs you penalties and the goodwill that made the next negotiation possible. Agreed terms are an asset. Taken terms are a debt you are not accounting for, and they damage the supplier relationships that made the terms available in the first place.
On the receivables side. State the terms on the invoice, not in the contract no one rereads. Print an actual due date, because "net 30" on its own is the ambiguity this article opened with, and your customer's AP clerk will resolve it in their favor. Set credit terms before the first order rather than after the first late payment, when the conversation is adversarial.
Match the two where you can. If your customers pay in 45 days and you pay suppliers in 30, you are carrying the difference. If a supplier will not extend terms, that is a signal to look more closely at DSO.
Payment timing is the whole game here, and payment scheduling turns agreed terms into realized cash flow. Paying everything on receipt is common in small businesses and is a habit, not a decision. Paying on the due date, deliberately, is free money.
Fix the invoice processing cost before anything else
Manual invoice processing is where small businesses lose the most time for the least return, and it's where the numbers are unambiguous.
Ardent Partners' State of ePayables 2025 puts the average cost to process a single invoice at $9.84, taking 8.2 days, with 18.4% of invoices raising an exception that needs a person. The same research found 57% of suppliers can now send invoices electronically, which means nearly half still cannot, and that is where most of the manual handling sits.
The Hackett Group's research on top-performing procurement organizations found they run with 31% fewer full-time staff at 19% lower cost.
Approval is only part of the distance. APQC's cross-industry benchmarking puts the median cycle time from invoice receipt until payment at 15.0 days, across 2,226 organizations. The difference between the two figures is where discounts are lost and where suppliers start calling.
What manual processing costs. An invoice arrives, usually by email, sometimes on paper. Someone reads it, works out what it relates to, forwards it for approval, chases the approval, keys it into the accounting system, files it, and then answers a question about it three weeks later.
Paper invoices make this worse, but email is not much better, since both leave the document sitting in a personal inbox. Manual data entry is the visible part and the smallest part. The investigation is the expensive part.
What to change, in order
Get invoices into one place. A single inbox or capture point, so nothing lives in an individual's mail. This is the cheapest change and removes the most chaos.
Match to a purchase order. An invoice with a PO reference can be checked automatically against what was agreed. An invoice without one is a question. This is the highest-value control in the whole accounts payable process, and it makes the rest of automation possible.
Capture the data instead of typing it. Optical character recognition on the invoice reduces data entry to review. Accuracy is good enough now that the exception, not the rule, is the manual case.
Route approvals by rule. Approval workflows that branch on amount and category clear routine invoices in minutes and escalate only what needs a decision. Approval processes that depend on one person create the payment delays that generate the late fees.
Connect to the accounting system. AP automation software that writes into your ledger, not beside it, removes the reconciliation entirely. Larger suppliers may also offer electronic data interchange, which eliminates the document step altogether, though for most small businesses PO matching delivers most of the benefit at a fraction of the setup. This is where cost savings stop being time saved and become work that no longer exists.
5 payment controls every small business needs
This is the section most small business AP advice skips, and the evidence says it should not.
The ACFE's 2026 Report to the Nations analyzed 2,402 occupational fraud cases and put the median loss at $104,000, with the typical case running 12 months before anyone detected it. More than half of cases involved either a lack of internal controls or an override of controls that were already in place, and 43% were caught by a tip. The report's long-standing estimate is that organizations lose about 5% of revenue to fraud each year.
Two of those findings explain why small businesses are exposed. A 12-month detection window is a long time in a business where one person handles payments. And controls that exist but can be overridden are the normal state when the person approving is also the person paying.
Vendor impersonation is an external threat that lands in accounts payable and needs no insider at all. The AFP's 2026 Payments Fraud and Control Survey found 74% of organizations were hit by business email compromise.
Someone emails your AP function claiming to be an existing supplier with new bank details. The invoice looks right because it usually is right. The payment goes to the wrong account, and by the time the real supplier chases it, the money is gone.
Five AP internal controls prevent most of this, and none of them require software:
- Verify bank detail changes out of band. Confirm any request to change a supplier's payment details by calling a number you already have, never a number in the email. This one control shuts down the vendor impersonation scheme described above.
- Separate who approves from who pays. Payment authorization and payment execution should not sit with the same person. In a small business, this often means the owner holds one of them. That is fine, and it is the point.
- Require a purchase order above a threshold. No PO, no pay. It prevents unauthorized payments, and it makes duplicate payments visible, since a second invoice against the same PO is obvious.
- Check for duplicates on invoice receipt. Same supplier, same amount, similar date. Many duplicate payments are honest errors, and they are only found if something looks.
- Reconcile on a schedule someone owns. Accurate financial records are a byproduct of regular reconciliation, not of careful typing.
Payment accuracy is the other half of the same discipline. A payment sent to the right supplier for the wrong amount, or multiple times, can be just as hard to recover as a fraudulent one. In a small business, the AP team is often one person, which is precisely why these controls matter. Concentration of duties is the risk, and a verification habit is the cheapest mitigation available.
Early payment discounts, and the arithmetic that settles them
Early payment discounts are offered constantly and evaluated rarely. The arithmetic takes a minute and usually says take it.
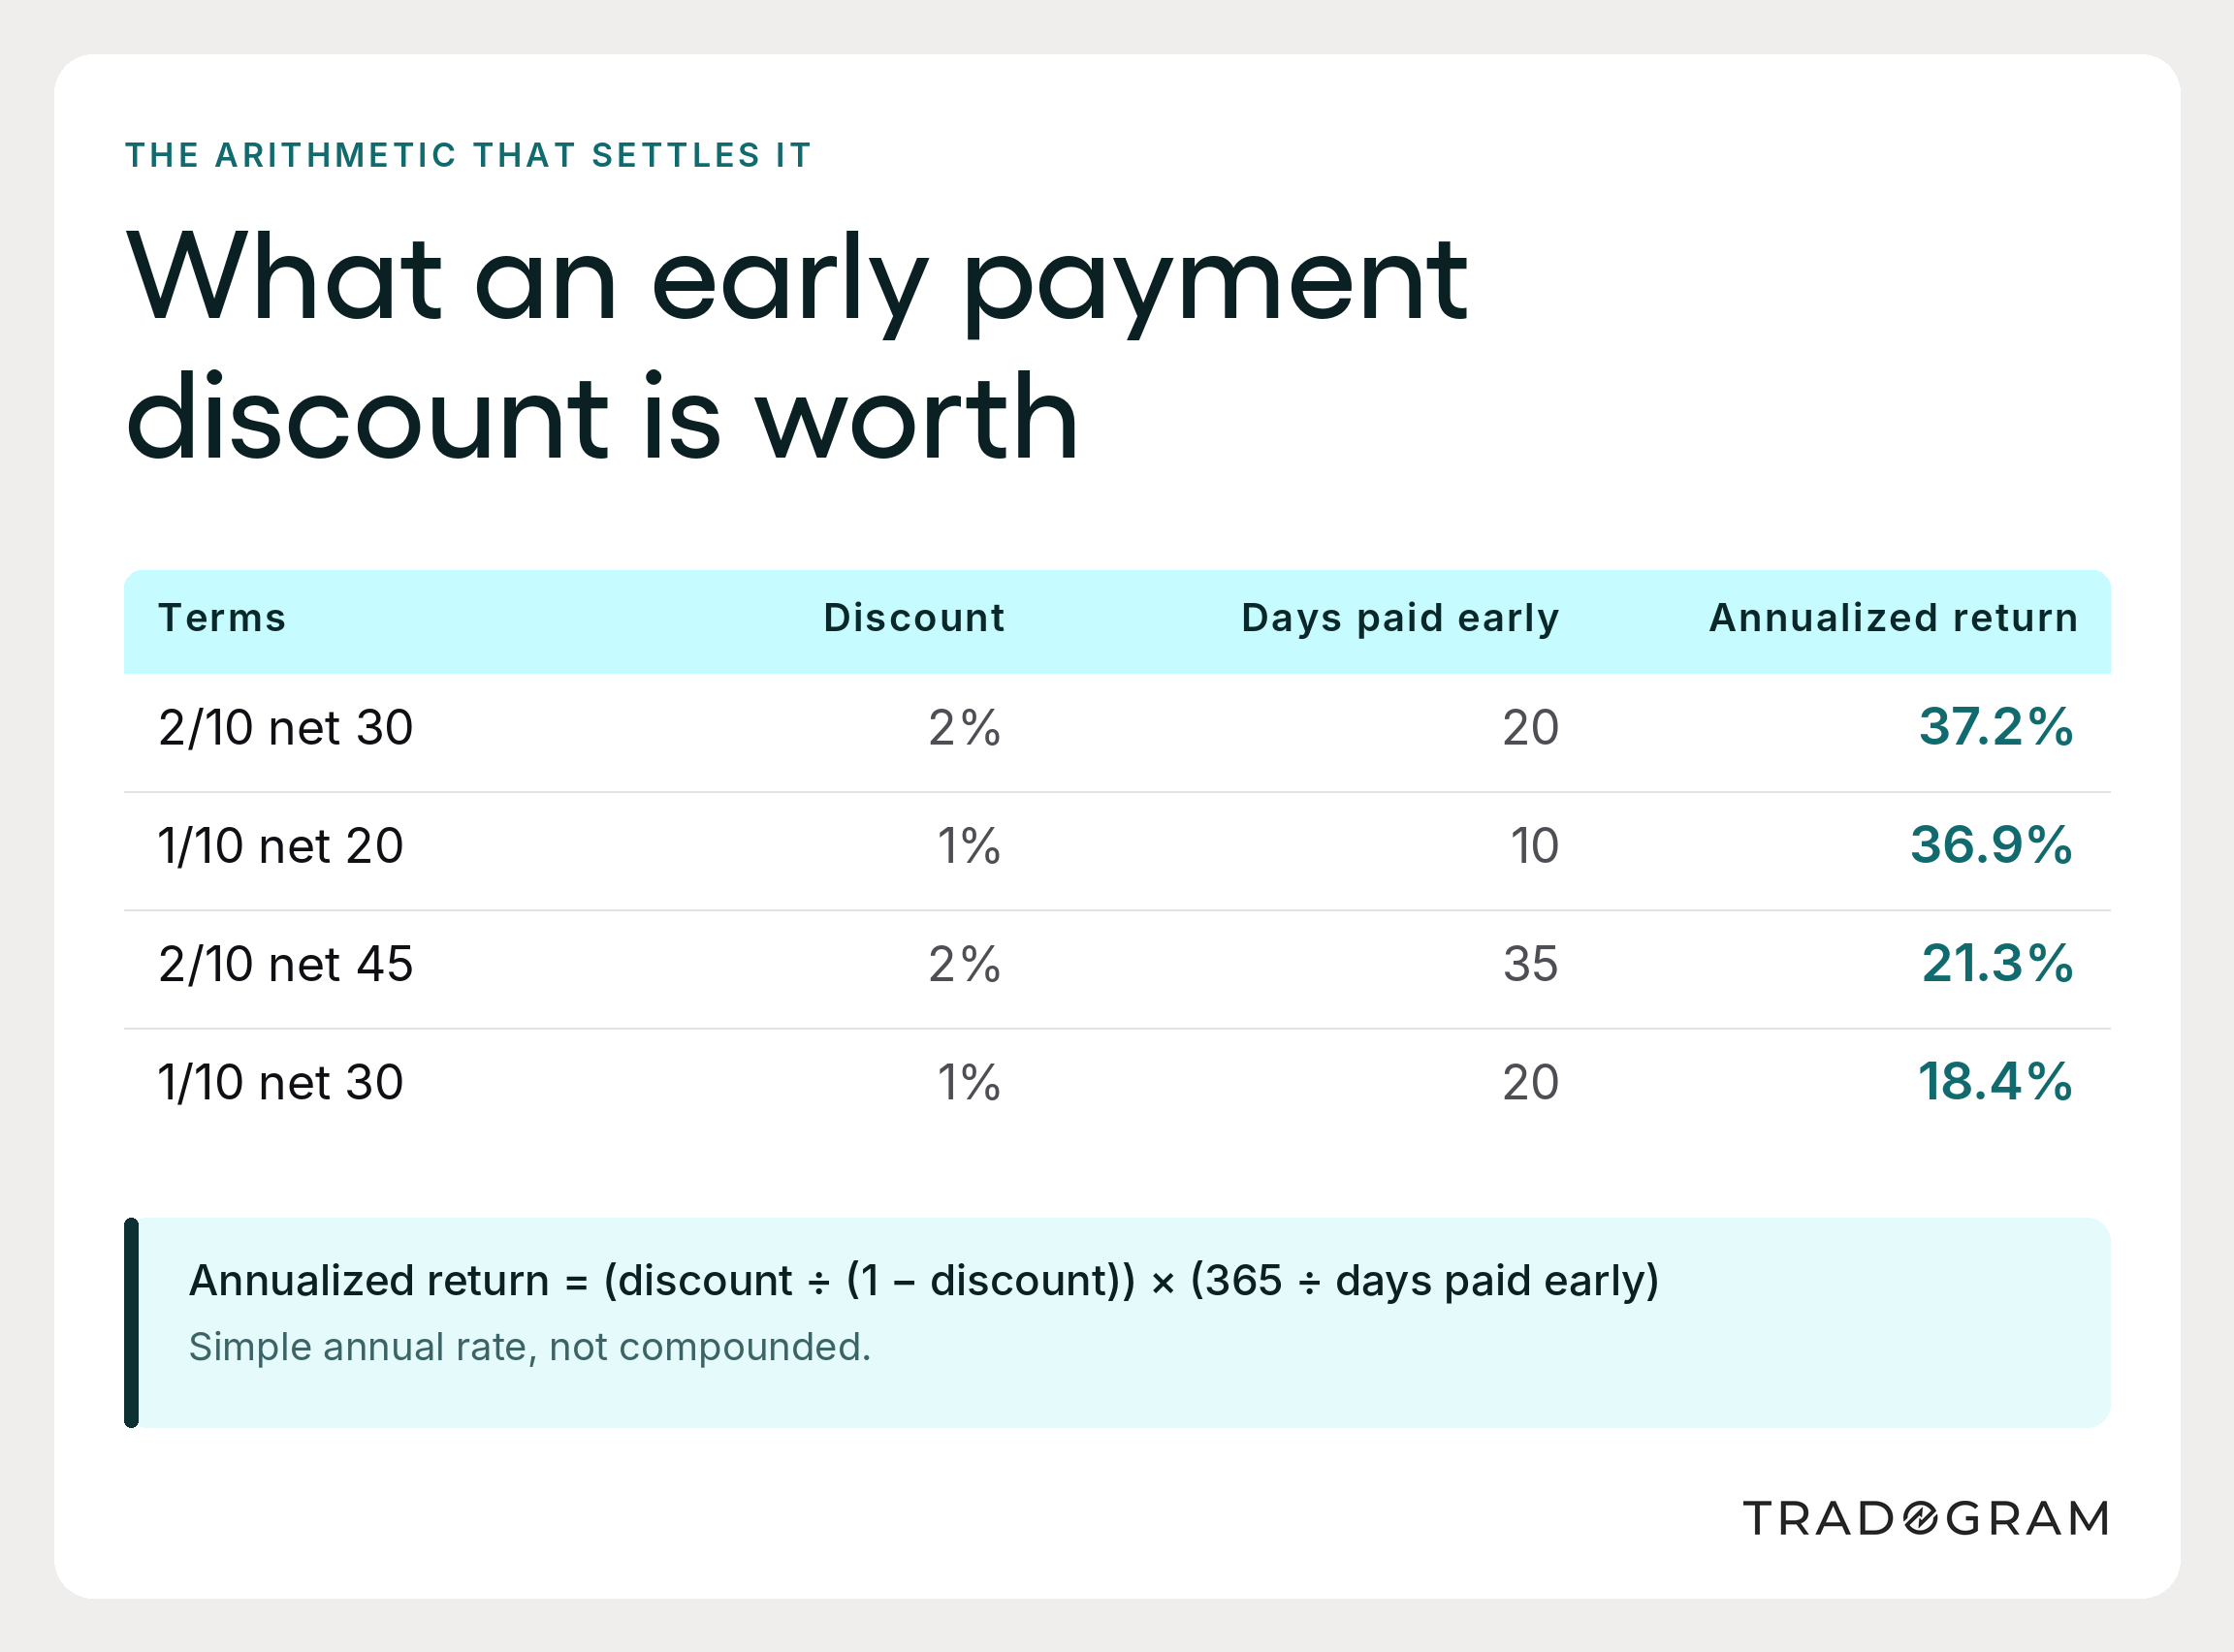
Standard terms of 2/10 net 30 mean 2% off if you pay within 10 days instead of 30. You are paying 20 days early to save 2%. Annualized:
(0.02 ÷ 0.98) × (365 ÷ 20) = 37.2%
A 37% annualized return, available on a recurring basis, on money you were going to spend anyway. Very little else a small business can do with short-term cash comes close.
The terms change the answer, so check. The same 2% for paying 35 days early, under 2/10 net 45, annualizes to about 21%. Still good. A 1% discount for paying 10 days early annualizes to roughly 37% as well, because the shorter window compensates for the smaller discount. The rule of thumb: the fewer days you pay early for a given discount, the higher the return, and small discounts over short windows are often better than they look.
Two conditions before you take them:
You need the cash without borrowing at a higher rate. If capturing a 37% annualized discount means drawing on a facility costing 12%, it is still worth it. If it means missing payroll, it is not.
You need to know your position ahead of time. This is the practical reason cash flow visibility matters. Discounts are decided in a narrow window, and a business that cannot see its position over the next two weeks will default to not taking them. That is the expensive default.
On the receivables side, the same logic runs in reverse. Offering customers 2/10 net 30 costs you the same 37% annualized. It earns its place when the alternative is a receivable at real risk, or when it converts a chronically slow payer into a reliable one. As a general policy, it fails because you will end up paying it to customers who would have paid on time anyway.
6 ways to get paid faster, without damaging the relationship
Receivables get less attention than they deserve in small-business advice, and the practices that work are unglamorous.
- Invoice immediately. The single biggest determinant of when you get paid is when you invoiced. Invoices sent weekly rather than on completion can add several days to DSO for no reason at all.
- Put the due date on the invoice as a date. Not terms. A date.
- Make paying easy. Multiple payment methods, including the ones your customers actually use. Payment friction is a real and underestimated cause of late payment, and it is entirely within your control.
- Chase before the due date, not after. A short, neutral reminder a few days before the due date tends to work better than a chase afterward, because it arrives as a courtesy rather than a complaint. It also surfaces disputes while there is still time to resolve them, and disputes are the usual reason an invoice sits unpaid.
- Segment your chasing. Not every late invoice deserves the same attention. Sort by value and by how late, and spend your time where the money is.
- Track payment status somewhere shared. If only one person knows which invoices are outstanding, collections stop when that person is away.
The same principle applies to suppliers and customers. You want to be the customer your suppliers prioritize and the supplier your customers pay first. Both come from being easy to transact with and predictable. Those are process characteristics, and you can redesign a process in an afternoon.
The numbers that tell you whether it is working
Six key AP metrics, plus their receivables counterparts, cover almost everything a small business needs.
| Metric | What it tells you | Watch for |
|---|---|---|
| Cost per invoice processed | Whether your AP process is efficient | Anything above the $9.84 average suggests too many manual touches |
| Invoice cycle time | Days from invoice receipt to payment approval | Rising cycle time usually means an approval bottleneck, not volume |
| Exception rate | Proportion of invoices that do not reconcile | Above 20% usually points upstream to purchase order discipline |
| Days payable outstanding | How long you take to pay | Read alongside DSO, never alone |
| Days sales outstanding | How long customers take to pay | The gap to DPO is the number that matters |
| On-time payment rate | Proportion of supplier payments made by the due date | The metric that determines whether terms negotiations go well, and the clearest signal of financial health to a supplier |
| Early payment discounts captured | Discounts taken against discounts available | A low rate almost always means poor forecasting |
Each of these points to a different fix. A high cost per invoice is an automation problem. A high exception rate is a procurement problem that shows up in AP. A poor on-time payment rate is a scheduling problem. Treating all of them as "accounts payable needs to improve" is how small businesses spend effort in the wrong place.
These numbers also connect to the rest of the business. Accounts payable sits on the balance sheet as a current liability, and financial data that is accurate in the ledger but two weeks behind reality won't support a decision. Effective AP management is largely about closing that lag.
Where accounts payable meets procurement
Most accounts payable problems are not created in accounts payable.
An invoice that cannot be matched, arrives without a purchase order, or includes a price nobody agreed to is an AP symptom of a procurement cause.
The payment process is rarely where the problem started, but the AP department absorbs the investigation, and from the outside it looks like accounts payable is slow. In fact, it is reconciling decisions made upstream without documentation.
This is the strongest argument for connecting procurement processes to the payable process:
Purchase orders make invoices checkable. An invoice against a PO is arithmetic. An invoice without one is an inquiry.
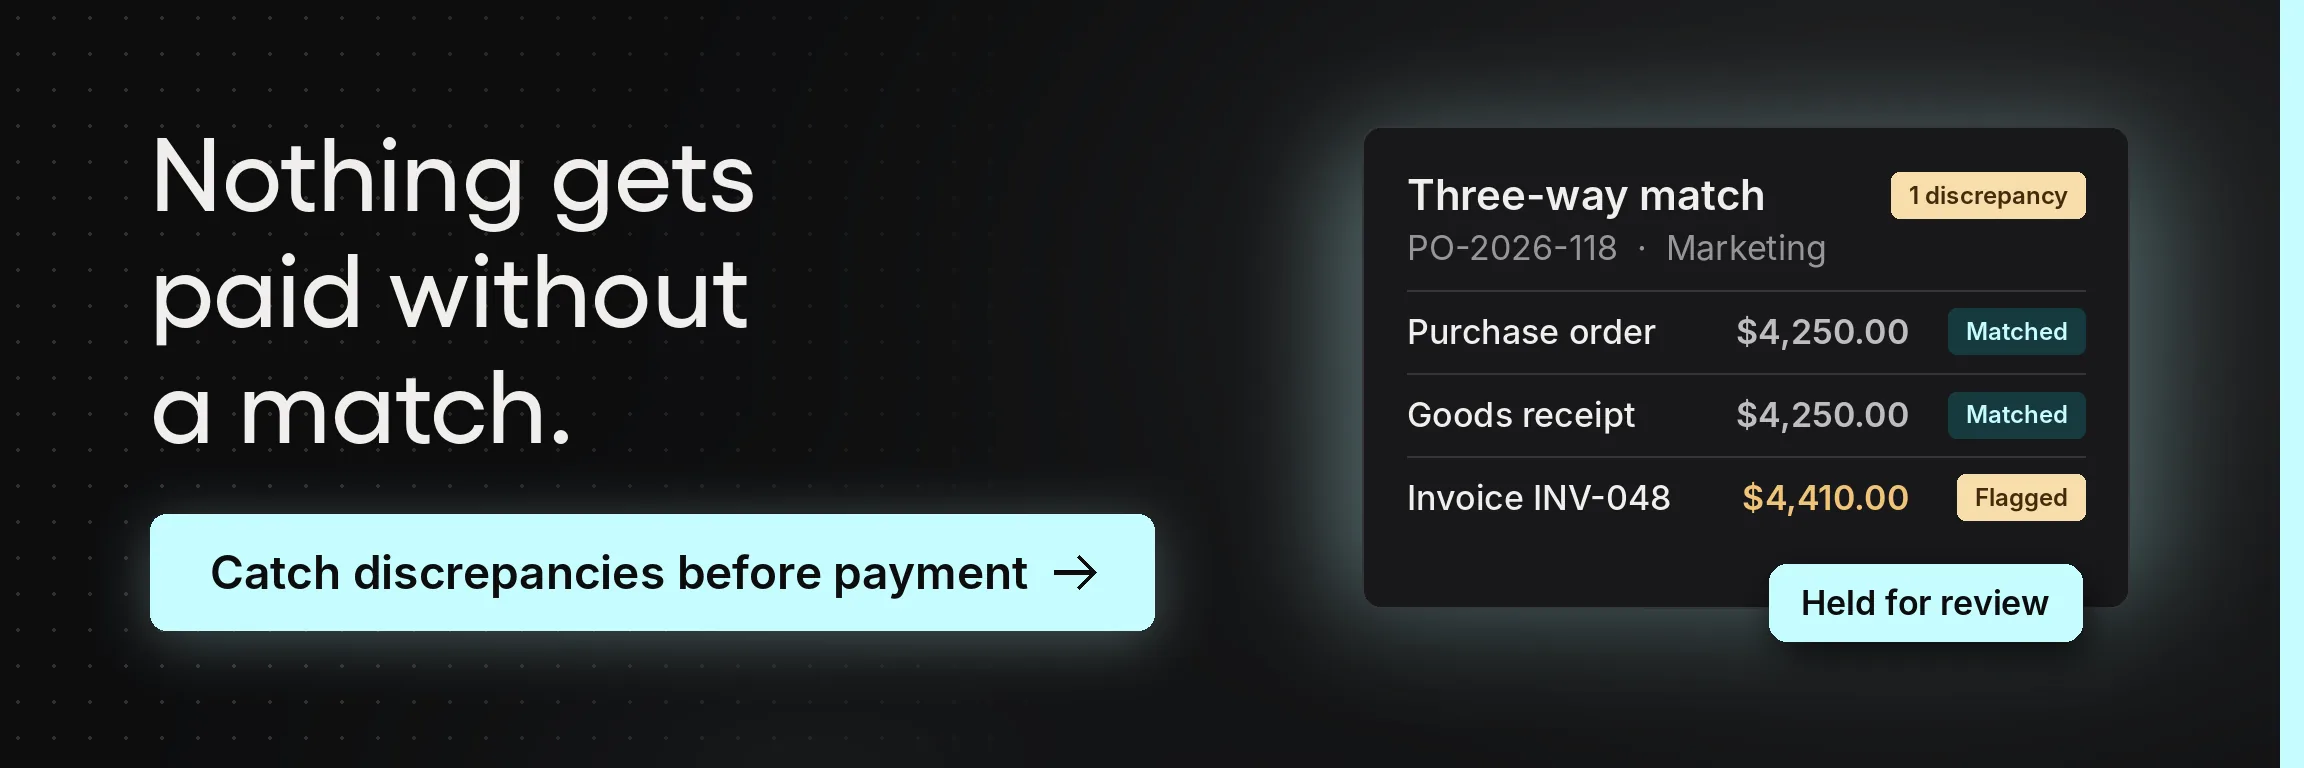
Receiving records make three-way matching possible. Comparing invoice, PO, and receipt catches goods billed but never delivered. Without the receiving record, you have a two-way match, which catches differences against the order but not goods that never arrived.
Committed spend becomes visible before the invoice. Open purchase orders tell you what is coming. This converts cash flow management from reactive to planned, and it is unavailable to a business that only sees a cost when the bill arrives.
Supplier records stay consistent. One supplier master serving both procurement and finance teams eliminates the duplicate-vendor problem that causes both matching failures and duplicate payments.
Purchase orders aren't free, which is why the threshold matters. APQC's benchmarking puts the cost to process a single purchase order anywhere from $14 to more than $54, depending largely on how the work is structured. Set the threshold above the value where raising the PO costs more than the control is worth, then hold it.
For a small business, the practical version is modest. You do not need a procurement department. You need purchase orders above a threshold, someone recording deliveries, and those records living where the person paying the invoice can see them.
What to do in the next thirty days
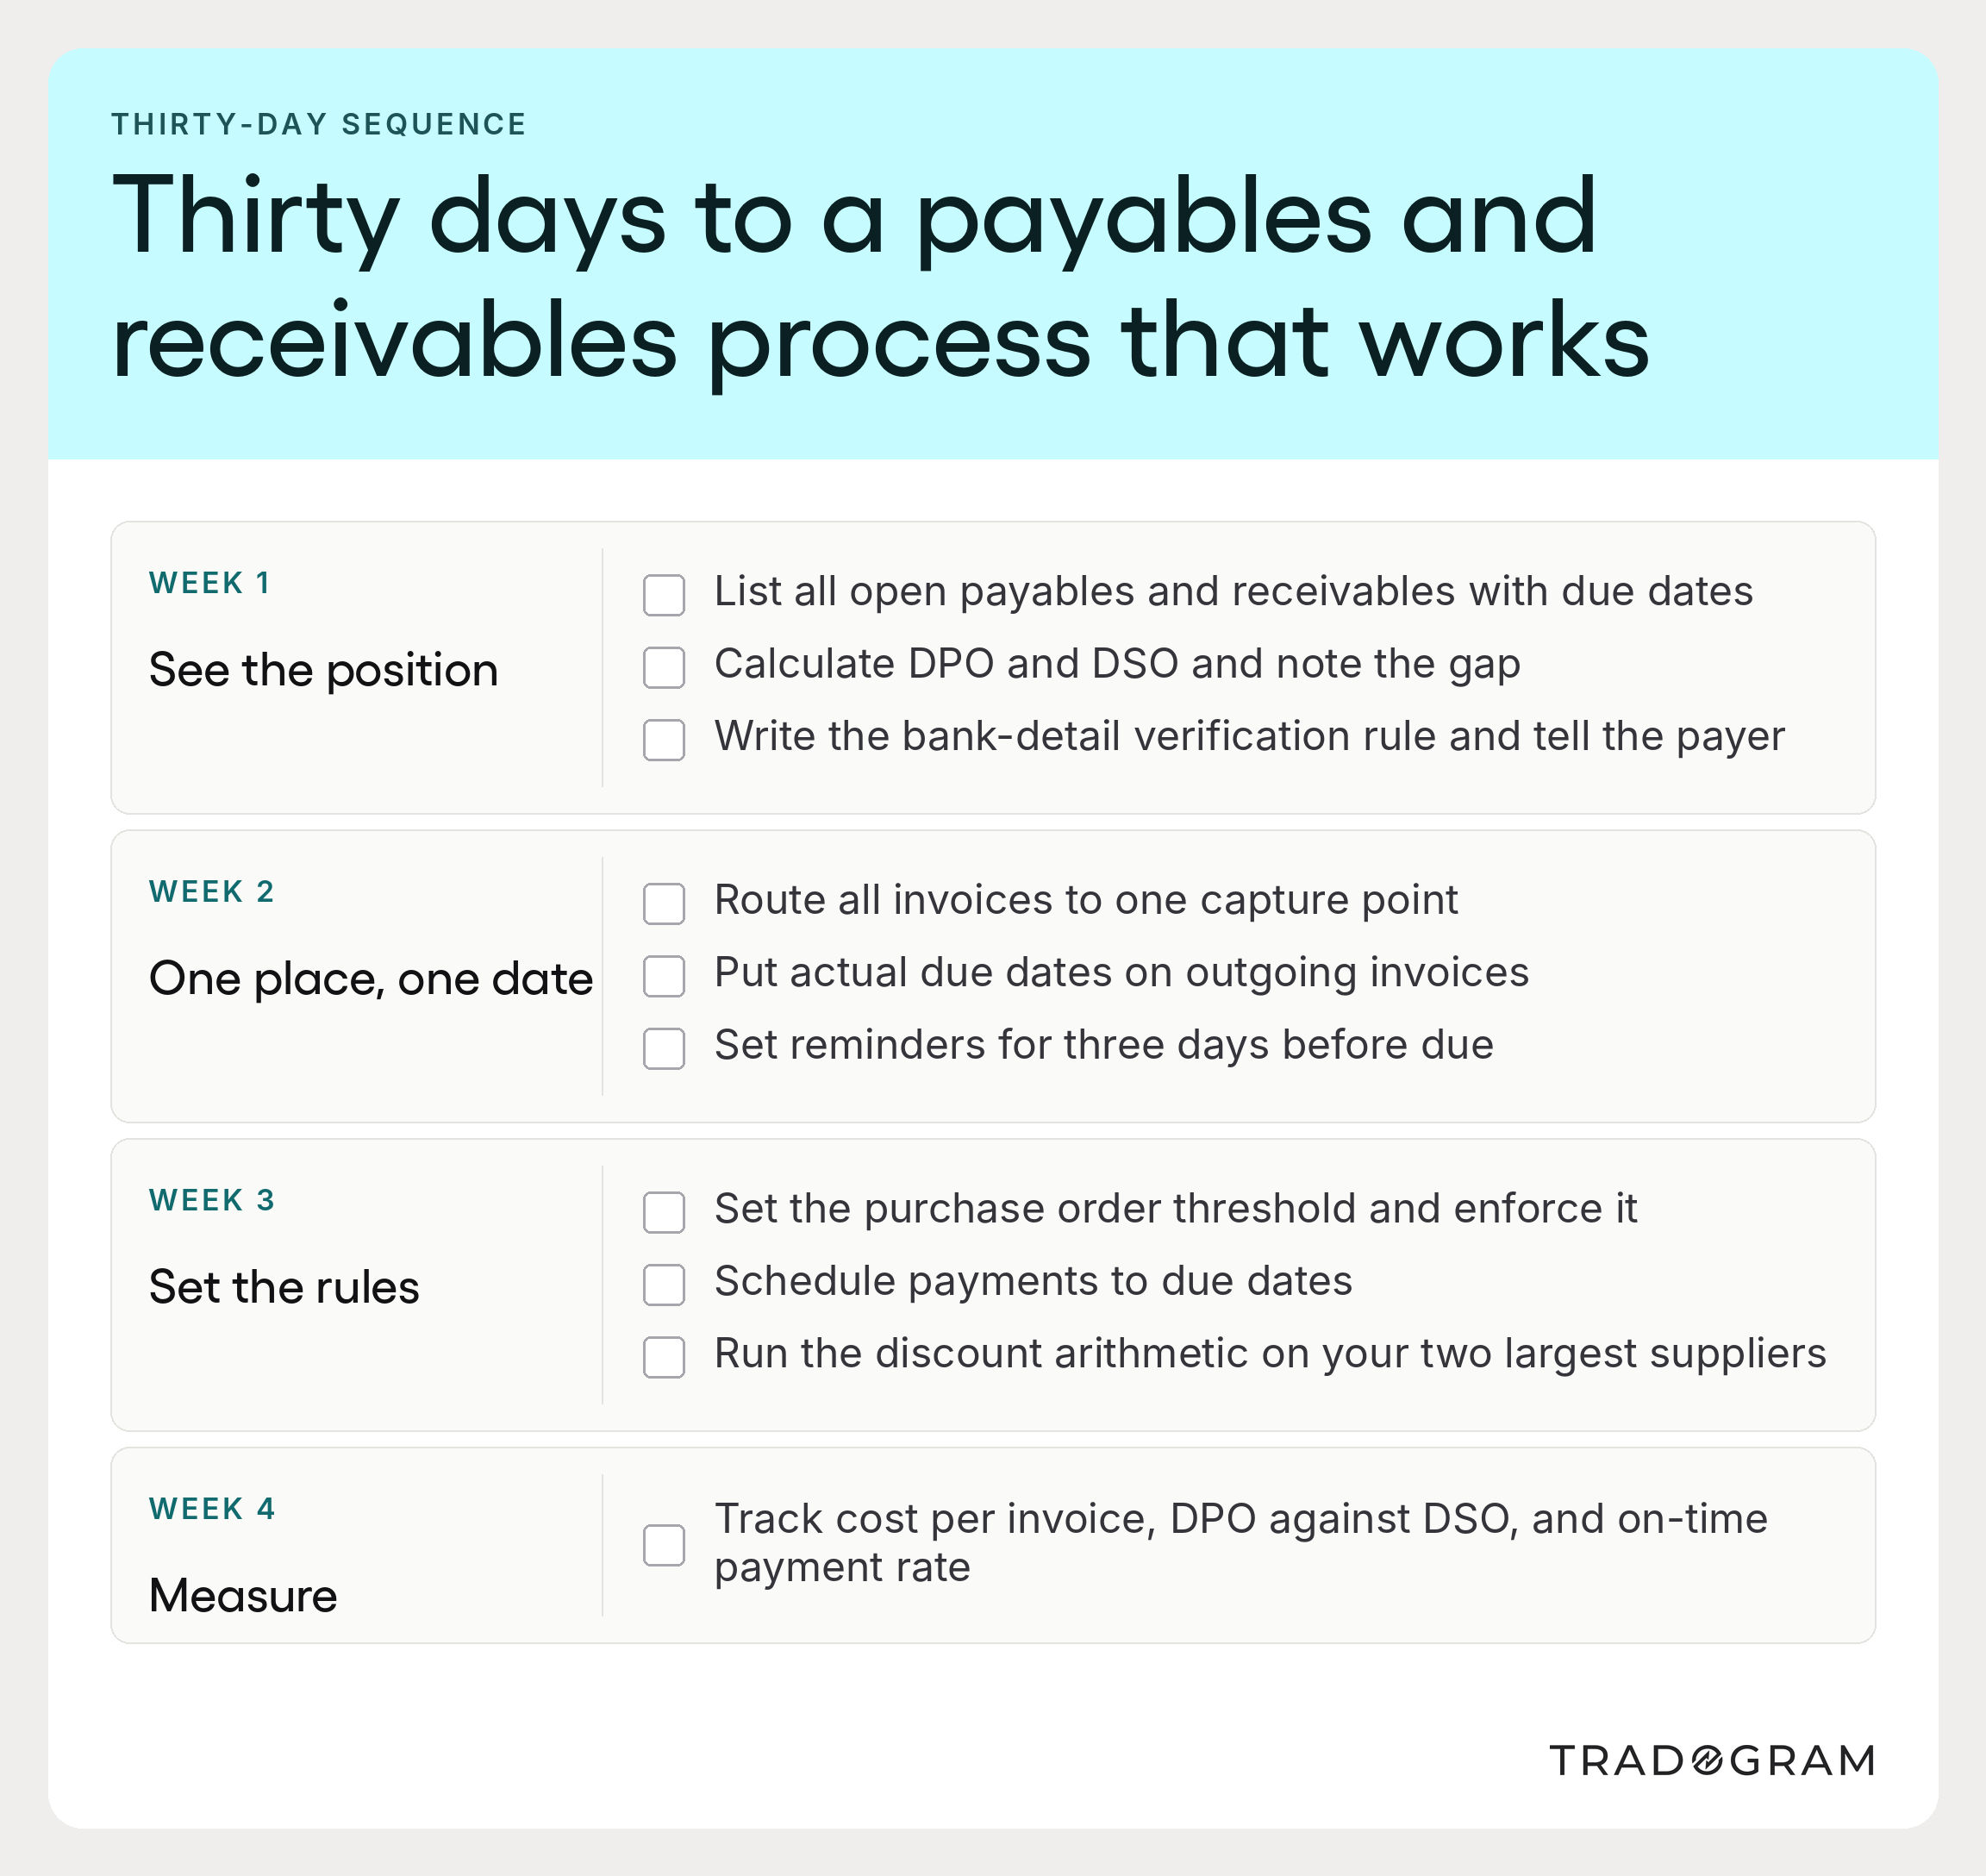
Accounts payable best practices tend to be presented as a list to adopt wholesale. That is not how it works in a business where the AP team is also doing three other jobs. This is a thirty-day sequence, ordered so each step makes the next one easier.
Week one: see the position. List every open payable and every open receivable with its due date. Most small businesses discover something in this exercise, usually an invoice that was not being tracked anywhere. Calculate DPO and DSO. The gap between them is your working number.
Week one: install the fraud control. Write down the rule that any change to supplier bank details is verified by phone to a number already on file. Tell whoever handles payments. This takes ten minutes, and it closes the opening vendor impersonation depends on.
Week two: one inbox, one place. Route every incoming invoice to a single capture point. Stop invoices living in individual mailboxes. This is the change that makes everything after it possible.
Week two: state your terms. Put actual due dates on outgoing invoices. Set up a reminder that goes out three days before, not seven days after.
Week three: introduce the purchase order threshold. Pick a value above which a PO is required. It does not have to be low. Enforce it, or the matching benefits never arrive.
Week three: schedule payments instead of paying on receipt. Pay on the due date deliberately. Check which suppliers offer early payment discounts and run the arithmetic on the largest two.
Week four: pick three metrics and start. Cost per invoice, DPO against DSO, and on-time payment rate. Do not build a dashboard. Write them down monthly.
In our experience, businesses that work through this find the same thing: cash flow improves less from any single change than from knowing the position early enough to make ordinary decisions on time.
At this size, an accounts payable strategy is about getting invoices paid on schedule, capturing discounts, and removing surprises. None of it requires an AP system more sophisticated than the business itself.
Where Tradogram fits
Everything in the thirty-day plan works on paper, and for a small business, that's the right place to start. It stops scaling with volume: more suppliers, more invoices, and more people making purchases than one person can keep track of.
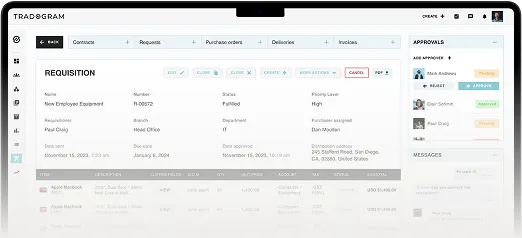
Tradogram keeps the payables side of this in one place. Requests and approvals follow the thresholds you set, and purchase orders and deliveries are recorded against the same supplier record.
When an invoice comes in, TradoScan reads it and surfaces anything that doesn't match the order or the delivery, so exceptions are resolved before payment. Those records connect with the accounting system you already use, so committed spend is visible before the invoice arrives and month-end starts from matched records.